
What Is an Emergency Fund?
An emergency fund is a dedicated amount of money saved for unexpected and necessary expenses. It is different from money you save for holidays, shopping, or other planned purchases.
For example, if your phone suddenly needs an expensive repair or you face an unexpected medical expense, an emergency fund can help you cover the cost without affecting your regular monthly budget.
Why Is an Emergency Fund Important?
Unexpected expenses can happen at any time. Without savings, you may need to borrow money or use funds intended for other important expenses.
An emergency fund can help you:
Handle unexpected expenses
Reduce financial stress
Avoid unnecessary borrowing
Protect your regular monthly budget
Prepare for temporary income loss
The goal is not to build a large amount of money immediately. Instead, it is to develop a consistent saving habit.
Step 1: Set a Realistic Savings Goal
A common goal is to build an emergency fund that can cover several months of essential living expenses. However, the right amount depends on your income, expenses, and personal circumstances.
Practical example:
Suppose your essential monthly expenses are:
Rent and utilities: $150
Food: $100
Transportation: $50
Other essential expenses: $50
Your total essential expenses are $350 per month.
If you want to build an emergency fund covering three months of essential expenses:
$350 × 3 = $1,050
Your target emergency fund would therefore be $1,050.
Step 2: Start With a Small Amount
You do not need to save $1,000 immediately. Starting with a small and consistent amount can make the goal easier to achieve.
Practical example:
If you earn $500 per month and save $50 every month:
$50 × 12 months = $600
After one year, you could have $600 saved for emergencies.
If your financial situation improves, you can gradually increase your monthly contribution.
Step 3: Include Emergency Savings in Your Budget
Treat emergency savings as part of your monthly financial plan. Set aside the amount you want to save before spending on non-essential items.
For example, if you receive $500 at the beginning of the month, you could immediately set aside $50 for your emergency fund and then plan the remaining $450 for your other expenses.
This can make saving more consistent and prevent you from spending the money before saving it.
Step 4: Keep Your Emergency Fund Separate
Keeping emergency savings separate from your everyday spending money can make it easier to avoid using the fund unnecessarily.
For example, you could keep your emergency savings in a separate savings account. This can help you clearly distinguish between money available for daily spending and money reserved for emergencies.
Step 5: Use It Only for Real Emergencies
An emergency fund should be used for unexpected and necessary expenses rather than regular purchases.
Example:
Buying a new phone because you want an upgraded model is generally not an emergency.
However, if your essential device suddenly breaks and you need to replace it for work or study, your emergency fund may help cover the unexpected cost.
After using your emergency fund, consider rebuilding the amount gradually.
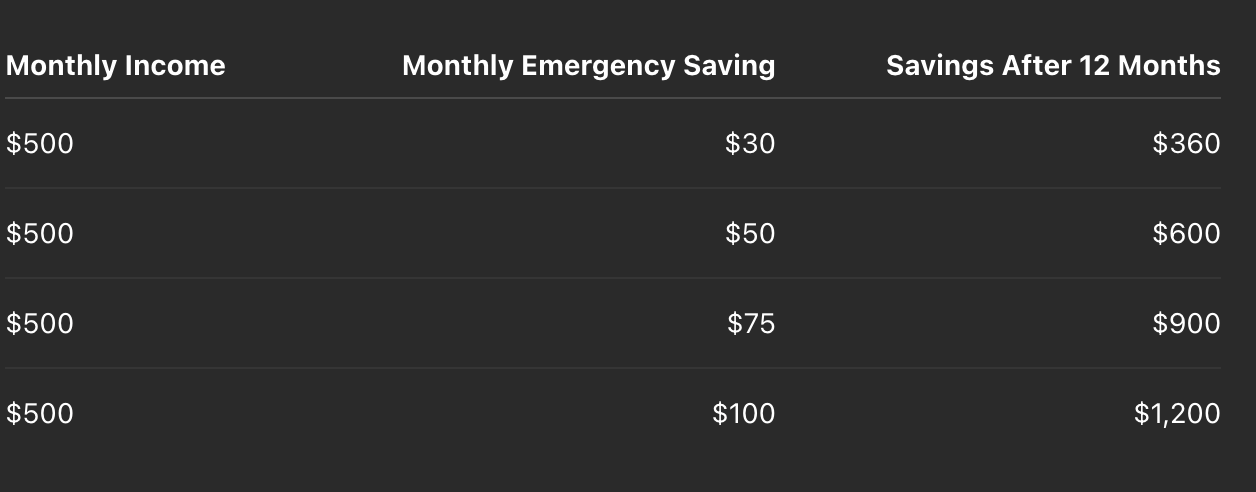
A Simple Emergency Fund Plan
Here is an example of how someone earning $500 per month could start:
Conclusion
Building an emergency fund is an important part of responsible financial planning. You do not need to start with a large amount. By setting a realistic goal, saving regularly, keeping your emergency savings separate, and using it only when necessary, you can gradually build a financial safety net.
Financial situations are different for everyone, so it is important to consider your income, essential expenses, and financial responsibilities when deciding how much to save.
At Delightech, we provide financial service solutions to support individuals and businesses with their financial needs. Developing good financial habits and understanding your options can help you make more informed decisions and prepare for unexpected financial challenges.


